 From FII Dependence to the Domestic Cushion
For much of India’s post-liberalisation history, foreign institutional investment was treated almost as a certificate of economic confidence. When FIIs bought Indian equities, the narrative was that global capital believed in India. When they sold, policymakers, markets and the media worried about instability. Something important has changed. India has built a much deeper domestic investor base through mutual funds, systematic investment plans, insurance, pension savings and direct retail participation. This is a major structural achievement. But it also creates a new danger: the belief that domestic money can indefinitely substitute for foreign capital, irrespective of valuation, taxation, global competitiveness or market returns.
That assumption deserves much greater scrutiny.
The Eight-Week Question
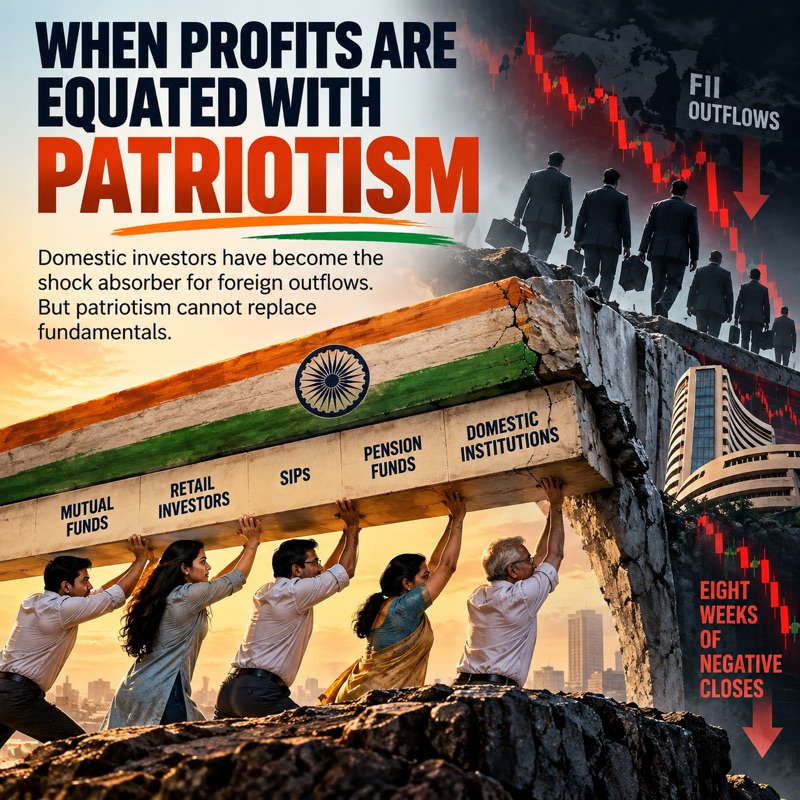
As of 25 September 2026, the Sensex and Nifty had actually completed seven consecutive negative weeks, their longest such sequence in about six years. On 28 September, both indices fell sharply again; if weakness persists through the week, it would become the eighth consecutive weekly decline. So the eighth negative weekly close has not yet been completed. (The New Indian Express)
More important than the number of weeks is what is happening underneath the indices. Foreign portfolio investors withdrew about ₹17,131 crore from Indian equities in September through the latest reported period. Another data compilation put foreign institutional selling at about ₹18,531 crore against approximately ₹52,617 crore of domestic institutional buying during September. (Akashvani News)
This is the remarkable feature of the present market: domestic capital is absorbing a substantial part of foreign selling, yet the market is still struggling.
That deserves more attention than the headline index itself.
The Domestic Investor Has Become the Shock Absorber
Historically, emerging markets feared what was sometimes called sudden-stop economics: foreign capital entered rapidly during periods of global liquidity and departed equally rapidly when interest rates, currencies or perceptions of risk changed.
India has partially reduced this vulnerability by creating its own pool of financial capital. That is unquestionably valuable. A country of India’s size should not require foreign portfolio managers to determine the price of its productive assets.
But resilience can quietly become complacency.
If policymakers begin assuming that households will continue putting money into mutual funds and markets regardless of relative returns, valuations or taxation, domestic investors cease being merely investors. They become the unofficial shock absorbers of the financial system.
There is a fundamental economic difference between the two roles.
An investor provides capital because expected risk-adjusted returns are attractive. A shock absorber provides capital because the system expects that money to keep arriving.
Patriotism Cannot Become an Asset-Pricing Model
This leads to an uncomfortable question: when does financial participation begin to be confused with economic patriotism?
Domestic investors are sometimes implicitly encouraged to think differently from foreign investors. Foreign capital can move to New York, London, Singapore, Tokyo or another emerging economy when relative returns change. Indian households, meanwhile, are expected to remain committed to the domestic growth story.
But capital does not acquire a different economic logic merely because its owner is Indian.
A retired employee investing pension savings, a salaried worker making a monthly SIP and a small entrepreneur putting surplus money into equities are not providing development assistance to the economy. They are allocating savings.
They deserve returns commensurate with risk.
Patriotism may influence consumption or national sentiment. It cannot permanently replace price discovery.
Taxation and Capital: The Story Is More Complicated
The taxation argument also needs precision. India raised the tax burden on certain capital gains in 2024: for example, the long-term capital-gains rate applicable to specified listed securities increased to 12.5% for transfers from 23 July 2024. (Etds)
But the current policy direction cannot simply be described as India continuously imposing additional taxes on foreign portfolio investors. In 2026, the government moved in the opposite direction in an important part of the capital market: it exempted qualifying FPI income from interest and capital gains on Indian government securities from income tax from 1 April 2026 and announced measures intended to facilitate foreign portfolio investment. (Press Information Bureau)
That makes today’s situation more interesting.
The larger issue is therefore not simply FII taxation versus domestic investors. It is whether India’s entire capital-market architecture—taxation, valuation, currency expectations, corporate earnings and regulatory predictability—remains internationally competitive.
Foreign Selling Is a Signal, Not a Verdict
It would also be misleading to attribute the present decline primarily to Indian tax policy.
Foreign selling has coincided with elevated US bond yields, expensive crude oil, geopolitical uncertainty and currency pressure. Recent market reporting identifies these global factors alongside sustained portfolio outflows as important drivers of the seven-week decline. (The New Indian Express)
Foreign investors have sold heavily over a longer period as well. Reuters reported this month that foreign investors sold nearly $45 billion of Indian equities across 2025 and 2026. (Reuters)
But FII selling should neither be worshipped nor dismissed.
Foreign capital can be short-term, momentum-driven and occasionally irrational. Yet persistent foreign selling can also be information. Global investors continuously compare India with alternative destinations on valuation, currency risk, taxation, earnings growth, liquidity and policy predictability.
The correct response to capital leaving is therefore neither panic nor nationalism.
It is diagnosis.
The Paradox of the Domestic Cushion
Imagine two markets.
In the first, foreign investors sell ₹100 and there are insufficient domestic buyers. Prices fall rapidly.
In the second, foreign investors sell ₹100 while domestic institutions buy ₹80. Prices decline much less.
Clearly, the second system is more resilient.
But now imagine this continues year after year. Foreign investors continuously reduce exposure while household savings continuously enter through institutional channels.
The apparent stability may begin concealing a deeper question:
Who is transferring risk to whom?
If foreign investors reduce positions at relatively high valuations while domestic savings continually absorb those shares, the system must eventually demonstrate that domestic buyers received adequate long-term returns.
Otherwise, financial deepening can unintentionally become financial risk redistribution—from globally mobile institutional capital toward domestically captive household savings.
That is the question India should examine before celebrating every month of record domestic inflows.
The Next Financial Revolution Must Be About Returns
India’s first capital-market revolution was foreign participation.
The second was democratisation: demat accounts, online trading, mutual funds, SIPs and millions of new household investors.
The third revolution must be more demanding.
It must be about quality of returns, governance, productivity and capital allocation.
Domestic liquidity cannot permanently compensate for weak earnings. SIP flows cannot indefinitely justify excessive valuations. Household savings cannot become an automatic buyer of last resort. And taxation cannot be designed on the assumption that investors have nowhere else to go.
Technology will make this increasingly important. Over the next decade, Indians will gain easier access to international securities, global ETFs, tokenised assets and cross-border investment platforms. Capital that appears domestically captive today may become far more internationally mobile tomorrow.
The government therefore cannot simply ask how much domestic money is entering the market.
It must ask why that money should rationally remain there.
From Atmanirbhar Capital to Competitive Capital
India certainly needs deeper domestic capital markets. An economy aspiring to become one of the world’s largest cannot remain excessively dependent on foreign portfolio flows.
But financial self-reliance should not mean financial insulation.
The strongest market is not one where domestic investors keep buying because foreign investors are leaving. It is one where domestic and international investors independently conclude that Indian productive assets offer attractive long-term returns.
That distinction will become crucial.
Foreign capital should not be treated as a master whose departure creates panic. Domestic capital should not be treated as a patriotic reserve army expected to defend market valuations.
Both should face the same fundamental economic proposition:
Is India generating enough productivity, profitability and future cash flow to justify the price investors are being asked to pay?
That is ultimately the test that no amount of liquidity can permanently avoid.
The dangerous moment begins when a country starts confusing capital-market resilience with guaranteed domestic loyalty, liquidity with productivity, and profits with patriotism.
Markets do not ultimately reward patriotism.
They reward the productive use of capital.
#IndianEconomy #StockMarket #FII #DomesticInvestors #CapitalMarkets #Investment


No comments:
Post a Comment