When water becomes more valuable than sugar
For decades, India’s sugar economy has been built around a simple assumption: grow more sugarcane, crush more cane, produce more sugar and support millions of farming households. Governments encouraged production through assured prices, mills expanded their capacities, and entire rural economies developed around sugarcane cultivation. What received far less attention was the enormous quantity of water required to sustain this system.
That assumption is becoming increasingly difficult to defend.
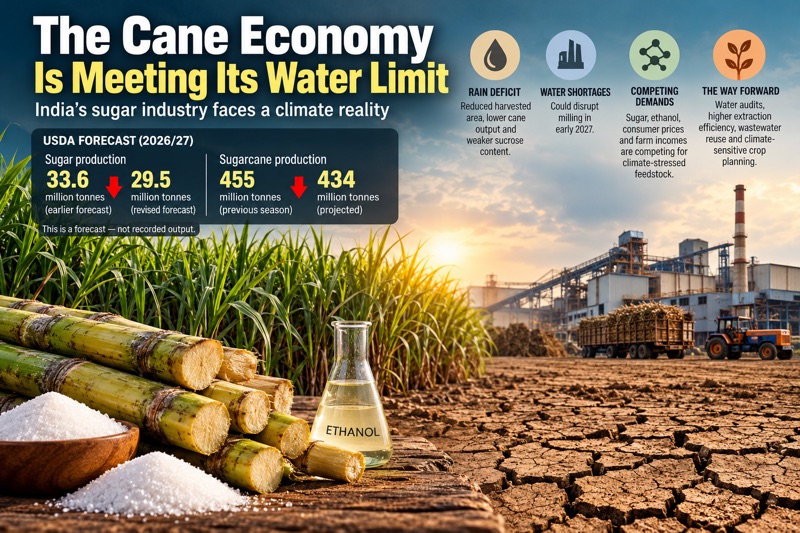
On 8 October 2026, the United States Department of Agriculture’s Foreign Agricultural Service reduced its forecast for India’s sugar production in the 2026–27 marketing year from 33.6 million tonnes to 29.5 million tonnes. Sugarcane production was projected to decline from 455 million tonnes in the previous season to 434 million tonnes.
These figures are forecasts, not actual production results. Nevertheless, they point towards a much larger economic problem. Severe rainfall deficits could reduce harvested area, cane production and sugar recovery. Water shortages could even interrupt milling operations in early 2027.
The immediate concern is lower sugar production. The deeper concern is whether India’s sugar economy has reached the ecological limits of its traditional production model.
A historical success is becoming an economic vulnerability
India’s sugar industry represents one of the most remarkable examples of agricultural industrialisation. Sugar mills became centres of rural economic activity, supporting farmers, transport operators, machinery manufacturers, traders and thousands of workers.
Cooperative sugar factories, particularly in Maharashtra, transformed local economies. Uttar Pradesh developed extensive sugarcane-based industrial networks. Government pricing policies provided farmers with greater income certainty than many competing crops.
Over time, sugarcane became more than an agricultural commodity. It became a political economy involving rural employment, farmer payments, industrial investment, consumer prices and government intervention.
But this success created an uncomfortable contradiction.
Sugarcane cultivation expanded in regions where water availability was becoming increasingly uncertain. Groundwater extraction compensated for inadequate rainfall. Irrigation subsidies and assured procurement reduced incentives to shift towards less water-intensive crops.
The economic system rewarded sugarcane production without adequately accounting for the declining availability of water.
India consequently developed a sugar economy in which private production decisions often depended on a natural resource whose growing scarcity was not fully reflected in costs.
The recovery crisis: More cane does not always mean more sugar
The latest production forecast exposes another weakness that is frequently overlooked.
Sugar production depends not only on how much sugarcane reaches a factory but also on how much sugar can be extracted from it.
When crops experience moisture stress, sucrose accumulation and recovery can suffer. Mills may therefore process substantial quantities of cane while producing less sugar.
The economics become particularly difficult because many costs do not decline proportionately.
Farmers still incur cultivation and harvesting expenses. Transporters continue moving cane to factories. Mills operate boilers, machinery and processing systems. Labour, maintenance and financing costs remain significant.
Yet the quantity of marketable sugar may fall.
This means a decline in recovery can damage profitability even when crushing volumes remain relatively strong.
For smaller mills and financially weaker sugar clusters, the consequences could be particularly severe. Lower recovery reduces margins, increases working-capital pressure and may delay payments to farmers.
The industry has traditionally measured its strength through acreage, cane arrivals and crushing capacity. The emerging climate economy demands a different measure: how much economically recoverable sugar can be produced from each unit of cane, water and energy.
Sugar and ethanol are entering the same resource competition
India’s sugar industry is no longer concerned only with supplying sugar to households and food-processing industries.
It is also an important participant in the country’s ethanol-blending programme.
Ethanol production has created an additional market for sugarcane-based feedstocks, encouraged distillery investment and offered mills opportunities to diversify revenues.
This has strengthened the commercial position of the industry. But it has also introduced another competing demand for the same agricultural resource.
When cane production is abundant, sugar and ethanol objectives can be managed with greater flexibility.
When production declines, difficult choices emerge.
Should available feedstock support domestic sugar consumption, ethanol blending, industrial demand or the financial stability of mills?
Every allocation has economic consequences.
Restricting ethanol production may affect distillery utilisation and blending plans. Diverting more feedstock towards ethanol can tighten sugar availability. Maintaining farmer prices during falling recovery can squeeze mill margins.
The problem is no longer simply one of agricultural production.
It is becoming a question of allocating climate-stressed agricultural resources among competing national priorities.
And there is an even more fundamental issue.
Ethanol may reduce dependence on imported petroleum, but the economic and environmental benefits of sugarcane-based ethanol cannot be evaluated without considering irrigation requirements, groundwater depletion and regional water stress.
A fuel that saves foreign exchange may still impose substantial local ecological costs.
The geography of sugar may have to change
Historically, sugar factories were established close to cane-growing areas because sugarcane is bulky, expensive to transport and loses quality after harvesting.
This created geographically concentrated sugar clusters.
Their locations reflected agricultural suitability, irrigation infrastructure, political decisions and historical investment patterns.
Climate change is now challenging some of these foundations.
Regions with extensive sugar-processing infrastructure may face increasing uncertainty in water availability. Areas with relatively favourable rainfall may become more attractive, although land suitability, competing crops and ecological limits will continue to matter.
The future competitiveness of a sugar cluster may therefore depend less on installed crushing capacity and more on the reliability of its surrounding water economy.
This raises a difficult question.
What happens when a district has enough factories to crush millions of tonnes of cane but insufficient sustainable water resources to grow that cane?
The answer cannot simply be another irrigation project or a larger subsidy.
India may eventually need to reconsider the geographical distribution of sugarcane cultivation, the location of processing investments and the incentives encouraging water-intensive production.
Such restructuring will be politically difficult because millions of livelihoods depend on the existing system.
But delaying adjustment could make the eventual economic disruption considerably more expensive.
Sugar clusters need water accounting, not just production targets
The immediate response should begin at the cluster level.
Sugar mills, distilleries, farmer organisations and state agencies need a shared information system connecting cane availability, expected sugar recovery, reservoir storage, groundwater conditions, irrigation demand and industrial water consumption.
A weekly cane–water–sugar balance could help identify emerging shortages before they become production crises.
Mills should plan procurement and crushing schedules around expected recoverable sugar rather than relying only on acreage estimates.
Investment priorities also need to change.
Improved extraction efficiency, condensate recovery, wastewater treatment and reuse, efficient cooling systems and reduced process losses can lower industrial water requirements.
At the farm level, better irrigation scheduling, drip irrigation where economically and technically suitable, improved soil-moisture management and appropriate crop varieties can reduce avoidable water consumption.
However, efficiency improvements must be accompanied by limits on unsustainable extraction. Otherwise, water saved per hectare may simply encourage further expansion of sugarcane acreage.
This is an important lesson from agricultural history: greater resource efficiency does not automatically produce resource conservation.
Cluster institutions should therefore measure both water productivity and total water withdrawal.
The hidden danger is industrial overcapacity
Another problem deserves attention.
India has invested heavily in sugar mills, distilleries, storage facilities, transport networks and associated machinery.
These investments assume a reasonably predictable supply of agricultural feedstock.
If climate variability makes cane production increasingly unstable, factories may face repeated periods of underutilisation.
A mill designed for a particular annual crushing volume cannot automatically reduce its fixed costs when cane arrivals fall.
Distilleries face similar problems when feedstock availability becomes uncertain.
This creates the possibility of a new form of industrial overcapacity: factories with adequate machinery, labour and finance but insufficient climate-resilient agricultural raw materials.
The consequences could extend beyond sugar.
Banks financing mills and distilleries may face greater risks. Machinery suppliers could experience irregular demand. Transport businesses may suffer lower utilisation. Rural employment could become more seasonal and unpredictable.
The sugar economy may therefore become an early example of how climate change can undermine industrial assets without physically damaging factories.
The future will be decided by water, not installed capacity
Two possible futures are emerging.
In the first, sugar production approaches the revised forecast of 29.5 million tonnes. Lower availability could sustain pressure on prices, complicate ethanol allocation and require closer management of domestic supplies. Import decisions may become more important, depending on stocks, consumption and government policy.
In the second, rainfall improves and production recovers more strongly than expected. Sugar availability increases, prices stabilise and mills regain operating confidence.
But even a favourable harvest would not remove the underlying problem.
A good monsoon can temporarily ease water scarcity. It cannot guarantee the long-term sustainability of groundwater extraction or protect the industry from increasingly uncertain rainfall patterns.
India therefore needs to move beyond managing annual sugar shortages towards managing the long-term resource foundations of the industry.
Future sugar policy should integrate agricultural pricing, water availability, ethanol allocation, industrial efficiency and regional crop planning.
Farmers should be supported in moving towards more water-efficient cultivation and, where necessary, economically viable crop diversification. Mills should be encouraged to invest in resource productivity rather than capacity expansion alone.
Most importantly, government support should gradually reward sustainable production rather than simply larger volumes.
The uncomfortable conclusion: India may have enough sugar factories but not enough sustainable water
The sugar industry was built during an era when expanding irrigation, increasing acreage and installing more machinery were considered signs of agricultural progress.
The coming decades will operate under different conditions.
Water will become more contested. Climate uncertainty will increase production risks. Energy and food-security objectives will compete for agricultural resources. Financial institutions will have to evaluate the environmental sustainability of industrial investments.
The central challenge is no longer how much sugarcane India can grow.
It is how much sugarcane India can afford to grow without undermining the water security of its future generations.
This changes the meaning of agricultural competitiveness.
A sugar cluster that produces more sugar while exhausting groundwater is not necessarily more competitive. It may simply be transferring today’s production costs to tomorrow’s economy.
India’s next agricultural transformation must therefore move from maximising output towards maximising sustainable value from scarce natural resources.
The future of the sugar industry will not be determined by the number of mills India builds or the tonnes of cane it crushes. It will be determined by how intelligently the country manages every drop of water supporting that production.
And that may be the most important economic lesson emerging from the 2026–27 sugar forecast.
Here are two separate, concise posts highlighting the economic and environmental challenges facing India’s sugar industry.
LinkedIn Post
The Cane Economy Is Meeting Its Water Limit
India may have enough sugar factories, but does it have enough sustainable water to keep them running?
The USDA has reduced its forecast for India’s 2026–27 sugar production from 33.6 million tonnes to 29.5 million tonnes. Sugarcane output is projected to decline from 455 million tonnes to 434 million tonnes.
This is more than a production warning. It exposes a deeper structural crisis.
India’s sugar, ethanol, farm-income and consumer-price objectives are increasingly competing for the same climate-stressed agricultural resources.
Lower sugar recovery means higher costs, weaker mill profitability and greater pressure on farmer payments. Meanwhile, water scarcity threatens the long-term viability of established sugar clusters.
The future requires a fundamental shift from maximising cane production to maximising economic value per unit of water.
Sugar clusters need water audits, efficient processing, realistic recovery estimates and climate-sensitive crop planning.
India’s next agricultural revolution will not be about producing more from more water. It will be about producing greater value with less water.
#IndianAgriculture #SugarIndustry #WaterSecurity #ClimateChange #Ethanol #AgriculturalEconomy #MSMEClusters #SustainableAgriculture #FoodSecurity #RuralEconomy
Facebook Post
🌾 The Cane Economy Is Meeting Its Water Limit
India’s sugar industry is facing a problem that cannot be solved simply by building more factories or growing more sugarcane.
The USDA has reduced its forecast for India’s 2026–27 sugar production from 33.6 million tonnes to 29.5 million tonnes.
The reason is worrying. Water shortages and poor rainfall could reduce cane production and sugar recovery.
But the real problem is much bigger.
Sugarcane needs substantial water. Sugar mills need cane. Ethanol plants compete for the same feedstock. Farmers need stable incomes, while consumers need affordable sugar.
Can India continue expanding this economy without considering its water limits?
The future of sugar production must focus on water efficiency, better farming practices, modern processing and sustainable agricultural clusters.
A good monsoon may save one season, but it cannot guarantee the future.
India must stop measuring agricultural success only in tonnes produced and start measuring how much water is consumed to produce them.
The next agricultural crisis may not begin with a shortage of factories or farmers. It may begin with a shortage of water.
#SugarIndustry #WaterCrisis #IndianAgriculture #ClimateChange #Ethanol #FoodSecurity #SustainableDevelopment


