Thursday, October 22, 2026

The Great International Economic Reordering: Who Will Control Value in 2035?


The future of global economic power may belong not to countries that manufacture the most, but to those that control the knowledge, technology, finance, standards and markets behind what the world consumes.

The World Is Entering an Age of Economic Control Rather Than Mere Production

For more than two centuries, international economic power was largely understood through a country's ability to produce, trade and accumulate wealth. Industrial output, export performance, natural resources and financial strength determined the relative position of nations. Countries that manufactured more were generally considered economically stronger, while countries exporting raw materials remained dependent on industrial powers. This distinction shaped colonial trade, industrial capitalism and much of the development thinking of the twentieth century.

By 2035, however, this traditional understanding of economic power may become increasingly inadequate. The central question will not simply be which country manufactures the world's goods, but which country controls the most valuable activities associated with their production, financing, distribution and consumption.

A country may manufacture millions of smartphones without owning their operating systems, semiconductor designs or global brands. Another may export enormous quantities of minerals while remaining dependent on foreign refining technologies and commodity trading networks. A third may possess a large digital workforce but remain dependent on foreign platforms, cloud infrastructure and artificial intelligence systems.

These countries participate in the world economy, but participation does not necessarily translate into economic control.

This distinction could become the defining feature of the international economic hierarchy over the coming decade.

From Industrial Empires to Global Value Chains: The Historical Transfer of Economic Power

The nineteenth century was dominated by industrial production and imperial trade networks. Britain emerged as a leading industrial power because it combined manufacturing technology, maritime transport, financial institutions and access to overseas markets. Industrialisation was not merely about factories. It was about controlling the systems through which raw materials, manufactured goods, capital and commercial information moved across borders.

The twentieth century gradually transformed this structure. The United States developed an economic system built around mass production, technological innovation, multinational corporations, petroleum, consumer markets and international finance. Following the Second World War, institutions such as the International Monetary Fund, World Bank and General Agreement on Tariffs and Trade helped establish a new framework for international economic coordination.

Economic power increasingly rested on the ability to combine industrial capacity with technological leadership, financial influence and institutional authority.

The period from the 1990s to the mid-2010s introduced another major transformation. Trade liberalisation, falling communication costs, containerisation and improvements in logistics enabled multinational companies to fragment production across countries. Manufacturing activities moved toward locations offering competitive costs, infrastructure and large labour forces.

China became the most prominent beneficiary of this transformation, developing an extraordinary manufacturing ecosystem supported by infrastructure, supplier networks, industrial capabilities and expanding technological competence.

Yet the globalisation of production also created a less visible division of economic rewards.

While manufacturing expanded across developing economies, many high-value activities remained concentrated in advanced industrial countries. Product design, intellectual property, specialised machinery, software, global branding, financing and distribution frequently generated greater economic returns than routine assembly.

The result was a world in which production became geographically dispersed, but control over many profitable functions remained concentrated.

The emerging international economic order may intensify this separation rather than eliminate it.

The Seven Invisible Pillars of Economic Power in 2035

The next international economic hierarchy may be determined by seven interconnected forms of control. These capabilities will overlap, reinforce one another and determine how much value different countries retain from their participation in global production.

Technology control: Ownership of knowledge may become more important than ownership of factories. Technological power increasingly depends on patents, semiconductor designs, artificial intelligence models, industrial software, proprietary production processes and accumulated engineering knowledge. A country may establish sophisticated manufacturing facilities but remain dependent on foreign suppliers for the technologies that make those facilities productive.

The critical issue is therefore not simply access to technology, but the ability to understand, adapt, improve and eventually develop it independently. Countries that remain permanent technology buyers may experience industrial growth without achieving technological leadership.

Financial control: The ability to finance production may determine who controls its direction. International finance influences investment decisions, exchange rates, trade settlement, debt sustainability and the allocation of capital. Reserve currencies, international banking networks, payment infrastructure and development finance provide significant strategic advantages.

Financial power also influences industrial ownership. Countries with abundant patient capital can invest in emerging technologies, absorb early losses and acquire valuable assets. Countries facing expensive capital and external financing constraints may struggle to build comparable capabilities.

By 2035, competition over payment systems, digital financial infrastructure and alternative development-financing arrangements could become increasingly important. However, the dominance of established financial systems will not disappear simply because alternatives are created. Trust, liquidity, institutional credibility and network effects remain formidable advantages.

Production control: Manufacturing will remain essential, but its strategic value will change. Manufacturing capacity cannot be dismissed in a world increasingly dependent on semiconductors, batteries, advanced machinery, defence equipment, pharmaceuticals and industrial automation.

Nevertheless, the strategic advantage will increasingly come from controlling entire production ecosystems rather than isolated factories. Supplier capabilities, tooling, industrial engineering, specialised skills, maintenance services and production flexibility will become central to competitiveness.

The difference between an assembly economy and an advanced manufacturing economy is not merely the sophistication of its factories. It is the depth of the domestic industrial ecosystem supporting them.

Resource control: Natural resources may become instruments of geopolitical influence. Energy, critical minerals, water, agricultural land and strategic materials will remain fundamental to industrial development. The transition toward electrification, renewable energy and advanced digital infrastructure could increase competition for selected minerals and processing capabilities.

Yet possession of resources does not automatically produce economic power. Countries exporting unprocessed minerals may capture only a limited share of the value generated through refining, component manufacturing and advanced applications.

The decisive question will be whether resource-rich economies can convert geological advantages into technological and industrial capabilities.

Market control: Whoever controls the customer may control a disproportionate share of value. Global brands, e-commerce platforms, distribution networks, procurement systems and customer data increasingly influence how value is distributed across supply chains.

A small manufacturer may produce an excellent product but remain dependent on intermediaries that control orders, pricing, product specifications and customer relationships.

The same problem exists in digital services. Countries may supply large numbers of programmers, designers and service workers while the platforms controlling customer access, intellectual property and recurring revenues remain elsewhere.

Market access and market control are fundamentally different economic capabilities.

Regulatory control: Standards may become the new instruments of economic competition. International trade is increasingly shaped by product standards, environmental requirements, cybersecurity rules, certification systems, data governance and supply-chain traceability.

Many such regulations serve legitimate objectives, including safety, sustainability and consumer protection. Nevertheless, compliance costs and unequal institutional capabilities can also create substantial barriers for smaller producers and developing economies.

By 2035, the ability to influence international standards and demonstrate compliance efficiently may become as important as conventional tariff negotiations.

Countries that participate in designing regulatory systems will possess advantages over those that merely struggle to comply with them.

Institutional control: The least visible but potentially most decisive form of power. Economic transformation requires coordination among government, industry, financial institutions, universities, research organisations and workforce-development systems.

Technology cannot be absorbed through subsidies alone. Industrial clusters do not automatically become innovative because firms operate near one another. Foreign investment does not necessarily create domestic supplier capabilities without deliberate institutional arrangements.

Countries capable of coordinating investment, learning, technology diffusion and structural adjustment will be better positioned to respond to rapid economic change.

Institutional quality may ultimately determine whether the other six forms of control reinforce one another or remain disconnected.

The Great Economic Paradox: More Exports, Less Control?

One of the most important contradictions in the emerging world economy is that a country can increase exports without proportionately increasing its control over economic value.

Gross export figures measure the value of goods and services crossing borders. They do not necessarily reveal how much domestic value is created, who owns the underlying technology or where profits ultimately accumulate.

A country exporting sophisticated electronics may depend heavily on imported semiconductors, foreign designs and overseas brands. Its export statistics may look impressive, while domestic technological capabilities remain limited.

Similarly, large inflows of foreign direct investment can expand employment, production and exports without automatically creating deep domestic industrial ecosystems.

This does not mean assembly operations or foreign investment lack economic value. They can generate jobs, wages, tax revenues and valuable learning opportunities. The concern arises when economies remain confined to these activities without progressively developing higher-value capabilities.

The central development challenge is therefore to transform participation into learning, learning into capability, and capability into greater economic control.

The United States, China, Europe and the Emerging Contest for Value

The United States enters this transition with major strengths in advanced research, digital platforms, semiconductor design, financial infrastructure, intellectual property and global brands. Its challenge will be to sustain technological leadership while strengthening critical industrial capabilities and managing the costs of strategic competition.

China possesses exceptional manufacturing scale, supplier ecosystems, infrastructure and growing capabilities in several advanced technologies. Its challenge is to reduce dependence on selected foreign technological bottlenecks while managing domestic financial pressures, demographic changes and restrictions on access to some international markets.

Europe retains important advantages in industrial machinery, specialised engineering, advanced materials, research institutions, premium brands and regulatory influence. However, fragmented capital markets, energy costs, demographic pressures and uneven digital-platform capabilities create challenges for its future competitiveness.

Japan and South Korea demonstrate how industrial capabilities, technological specialisation and sophisticated supplier networks can generate strategic influence beyond the size of domestic markets.

Resource-rich economies in the Middle East, Africa and Latin America may gain new opportunities from energy transitions and supply-chain diversification. But their long-term position will depend on whether they can move beyond resource exports toward processing, engineering, industrial services and technological capabilities.

The emerging order will therefore not be a simple contest between developed and developing countries.

It will be a competition among different combinations of technological, financial, industrial, resource and institutional strengths.

India in 2035: A Large Economy or a Powerful Value-Creating Economy?

India's economic future must be examined through this changing international framework.

The country possesses significant advantages: a large domestic market, a substantial entrepreneurial base, expanding digital infrastructure, a diversified industrial structure, scientific and technical talent, and opportunities arising from the diversification of global supply chains.

However, the critical question is whether these advantages can be converted into deeper technological and industrial capabilities.

India's development strategy has frequently emphasised investment, infrastructure, production capacity, exports and entrepreneurship. These are necessary foundations, but they are not sufficient to guarantee sustained economic upgrading.

A country can establish industrial parks without creating innovation ecosystems. It can attract multinational manufacturers without developing competitive domestic suppliers. It can expand digital transactions without owning globally influential digital platforms. It can increase exports while remaining dependent on imported technologies and foreign distribution networks.

India's strategic challenge is therefore not merely to become a larger manufacturing economy. It is to become an economy that controls a greater share of the knowledge, technology, engineering, branding and market relationships embedded in its production.

This requires a fundamental shift in industrial policy.

Instead of measuring success primarily through investment announcements, factory construction, employment numbers and gross exports, policy must increasingly examine domestic value addition, supplier upgrading, technological learning, intellectual property creation and international market ownership.

The distinction is important because industrial scale without capability accumulation may create vulnerability rather than lasting competitiveness.

### MSMEs and Industrial Clusters: The Missing Architecture of Economic Power

India's micro, small and medium enterprises will play a decisive role in determining whether the country can move toward higher-value economic activities.

Historically, industrial clusters have helped smaller enterprises overcome disadvantages of scale through specialised suppliers, shared labour markets, collective infrastructure and local knowledge networks.

However, many clusters remain concentrated in relatively low-value production activities. Firms compete primarily through prices, labour costs and delivery schedules, while product development, advanced technology, branding and customer relationships are often controlled elsewhere.

This model becomes increasingly vulnerable as automation reduces the importance of low-cost labour and international buyers impose more demanding requirements concerning quality, traceability, sustainability and delivery reliability.

The next generation of industrial cluster development must therefore move beyond common infrastructure and basic production assistance.

Clusters need shared design and engineering facilities, technology-extension services, product-testing laboratories, internationally recognised certification systems, digital traceability platforms, export-market intelligence and stronger connections with research institutions.

More importantly, they need institutional mechanisms through which enterprises can jointly acquire capabilities that individual firms cannot economically develop alone.

A cluster should not be considered successful merely because its production or exports increase. Its success should also be judged by whether local firms are moving from subcontracting into product development, specialised engineering, branding, technology ownership and direct customer relationships.

This requires changing the fundamental objective of cluster policy from improving production efficiency alone to increasing the capacity of firms to capture value.

Why Traditional Industrial Policy May Become Inadequate

Industrial policy in many developing economies has historically relied on subsidies, tax incentives, industrial estates, concessional finance and infrastructure development.

These interventions can address important constraints. However, they do not automatically create the organisational knowledge, engineering capabilities and market relationships required for sustained competitiveness.

The coming decade will require a more demanding approach.

Public support should increasingly be linked to measurable capability development. Supplier-development programmes should demonstrate technological upgrading. Research incentives should encourage commercial applications. Foreign investment facilitation should include opportunities for domestic supplier participation and skills development. Export promotion should support market diversification, product development and direct buyer relationships.

This does not mean every country should attempt to own every technology or vertically integrate every supply chain. Such an approach would be expensive, inefficient and often unrealistic.

Strategic autonomy should instead be understood as the ability to manage critical dependencies, develop selected capabilities and retain meaningful economic choices.

A country becomes economically stronger not by eliminating international dependence, but by reducing one-sided dependence and improving its bargaining position within global networks.

The New Risk: Economic Dependency Without Visible Colonialism

The emerging international economic order may create a form of dependency that differs significantly from traditional colonial relationships.

Countries may possess political sovereignty, expanding industries and growing exports while remaining structurally dependent on external technologies, financial systems, digital platforms and market-access rules.

The mechanisms of influence may be less visible than those of earlier centuries.

Technological licensing can shape production choices. Platform algorithms can influence market access. Financial restrictions can alter investment decisions. Certification systems can determine whether smaller firms can enter international markets. Control over critical inputs can affect entire industries.

These relationships are not inherently exploitative, and international specialisation can create substantial mutual benefits. The concern is the concentration of decision-making power and the limited ability of dependent economies to negotiate alternatives.

The future international economic debate may therefore increasingly concern not only inequality of income, but inequality of economic control.

Countries that lack strategic capabilities may discover that higher output and greater integration do not necessarily produce greater influence over their economic futures.

Looking Toward 2035: Five Possible Transformations

Several structural changes could reshape the distribution of international economic power by 2035.

First, artificial intelligence and industrial automation may reduce some advantages associated with low-cost labour, increasing the importance of engineering, energy reliability, computing infrastructure and technological adaptation.

Second, global value chains may become more regionally diversified without necessarily becoming less internationally interconnected. Firms may distribute production across several countries while keeping critical technologies and decision-making functions concentrated.

Third, environmental and digital standards may increasingly influence market access. Compliance capabilities could become a major dividing line between globally competitive firms and enterprises excluded from premium markets.

Fourth, the energy transition may redistribute strategic influence among countries possessing minerals, refining capabilities, battery technologies, electricity infrastructure and advanced industrial equipment.

Fifth, global finance may become more contested as countries experiment with alternative settlement systems and development-financing arrangements. Yet existing reserve-currency and financial networks are likely to retain significant advantages because of their depth, liquidity and institutional foundations.

These transformations will not necessarily produce a single dominant economic power. A more plausible outcome is a fragmented hierarchy in which different countries control different strategic functions.

A New Framework for Measuring National Economic Success

If economic control becomes more important, traditional measures of economic performance will need to be supplemented by new indicators.

GDP, export growth, manufacturing output and foreign investment will remain essential measures. However, they should be examined alongside domestic value added, technology ownership, research commercialisation, domestic supplier participation, brand ownership, engineering capabilities and the ability to influence international standards.

For India, a more meaningful industrial performance framework would ask whether domestic enterprises are acquiring proprietary knowledge, whether MSMEs are moving into higher-value activities, whether local suppliers are entering technologically demanding production networks, and whether Indian firms are gaining stronger access to international customers.

These indicators are harder to measure than production and exports. Nevertheless, they may provide a more accurate understanding of long-term competitiveness.

The ultimate purpose of industrial development is not simply to produce more goods. It is to build the capabilities that allow an economy to generate, retain and reinvest a growing share of the value created.

The World Will Be Divided Between Value Producers and Value Controllers

The great international economic reordering toward 2035 may not be defined by the disappearance of globalisation. Instead, globalisation itself may become more selective, technologically demanding and politically contested.

Production will continue to cross borders. International investment will remain important. Countries will still benefit from specialisation and trade.

But the distribution of economic rewards will increasingly depend on who controls the critical functions within these networks.

The nineteenth century demonstrated the power of industrialisation. The twentieth century demonstrated the importance of mass production, multinational corporations and finance. The early twenty-first century demonstrated the extraordinary potential of globally fragmented manufacturing.

The next decade may demonstrate something more fundamental: economic power increasingly depends on the ability to control knowledge, coordinate production, finance innovation, influence standards and maintain direct relationships with markets.

For India, the challenge is not simply to become a larger participant in the international economy. It is to acquire the technological, institutional and commercial capabilities necessary to influence how that economy operates.

For MSMEs and industrial clusters, the transition must be from low-cost subcontracting toward specialised knowledge, engineering, innovation, branding and customer ownership.

The countries that succeed will not necessarily be those that manufacture everything. They will be those that possess enough strategic capabilities to determine what they produce, how they produce it, where they sell it and how much value they retain.

By 2035, the most important dividing line in the global economy may no longer be between countries that produce and countries that consume, but between countries that participate in value chains and countries that possess the capabilities to shape them.

The ultimate economic question of 2035 will not be who makes the world's products, but who controls the decisions, technologies and markets that determine their value.

Analytical perspective | October 2026. This article presents a forward-looking interpretation of structural economic trends. Its projections for 2035 are scenarios, not established forecasts.

Wednesday, October 21, 2026

The Quiet Crisis Behind Stable Business Confidence

What Europe’s small firms reveal about investment, industrial resilience and India’s export strategy

An economy can look stable while its smaller businesses quietly stop preparing for the future. Factories continue operating, workers remain employed and orders keep moving. Yet machinery purchases are postponed, product development slows and entrepreneurs become reluctant to expand. The damage appears gradually, through capabilities that never develop and opportunities that firms cannot pursue.

This is the larger concern raised by SMEunited’s Autumn 2026 SME Business Climate Index and EU Craft and SME Barometer, released on 9 October. Headline confidence remained broadly stable for a third consecutive semester, while uncertainty continued to weigh on investment. Manufacturing remained the most affected sector for the eighth consecutive semester. Stability, in this setting, offers limited reassurance.

When stability becomes a low ceiling. A business confidence indicator records how firms assess their circumstances. It cannot, by itself, establish whether those circumstances are healthy. A company that has abandoned an expansion plan may feel more comfortable because it has reduced its exposure to risk. Its confidence can stabilise even as its ambitions shrink.

This creates a difficult policy question: are firms becoming stronger, or merely adjusting to weaker prospects?

The distinction matters because survival and development follow different paths. Surviving may require conserving cash, postponing recruitment and repairing old machines. Development requires spending before the benefits are certain. An economy can preserve much of its existing business activity while steadily weakening its capacity to compete tomorrow.

The long shadow of an industrial shock. SMEunited links manufacturing’s continuing weakness to the unresolved effects of the 2022 energy shock. Its latest assessment also reports that turnover and orders fell short of expectations, while price increases were stronger than anticipated, particularly in manufacturing and construction. These are survey findings and the association’s interpretation, rather than a causal measurement of each underlying pressure.

The historical lesson is that a shock can outlive the immediate disruption. When investment is repeatedly postponed, the consequences accumulate. Equipment ages, technical learning slows and the distance from more productive competitors may widen. Even when an input price falls, the investment missed during the difficult years does not automatically return.

A temporary crisis can therefore leave a lasting industrial inheritance. Recovery must be judged partly by whether firms resume upgrading, rather than solely by whether conditions stop deteriorating.

Small firms disappear inside large averages. The barometer’s practical strength is its recurring examination of firms by size and sector. It draws on twice-yearly surveys conducted through SMEunited member organisations, covering business conditions, turnover, employment, prices, investment and orders. Results distinguish micro, small and medium enterprises across manufacturing, construction and services.

That approach asks a better question than whether business confidence has improved overall: whose confidence, in which activity, and with what capacity to act?

A larger supplier may spread its risks across customers, products and markets. A micro enterprise dependent on two buyers has fewer options. Both may report stable turnover, but their ability to withstand a cancelled order or delayed payment can be radically different.

The same problem applies to export statistics. Higher export earnings can coexist with fewer participating suppliers, thinner margins or longer payment cycles. Aggregate growth does not reveal how widely opportunity is distributed across the production system.

For India, Europe is also a customer network. The implications extend beyond comparing European and Indian SME policies. For Indian exporters selling to European smaller businesses, weak investment intentions could affect demand for machinery, components and other business inputs. Buyers facing uncertainty might reduce order sizes, postpone commitments or seek longer credit periods.

These are possible transmission channels, not outcomes established by the European survey. They need to be tested against actual buyer behaviour.

Export institutions should therefore ask more precise questions. Are repeat orders becoming smaller? Are buyers shortening their planning horizon? Are enquiries converting into purchases? Are payment periods lengthening? A stable annual sales figure can conceal deterioration in several of these areas.

Such monitoring would help distinguish a temporary interruption from a change in the commercial relationship.

Build an early-warning system close to the workshop. India’s export promotion councils and cluster institutions should develop a regular picture of enterprise conditions that separates micro, small and medium firms. Four measures deserve particular attention: confirmed order books, investment intentions, payment delays and capacity utilisation.

These indicators become more useful when read together. Falling orders with rising receivables suggest a different problem from strong orders with inadequate production capacity. Weak investment despite available capacity may reflect uncertainty about future demand. Strong demand accompanied by payment delays may point towards a working-capital constraint.

The response should follow the diagnosis. Buyer diversification, receivables finance, technical support and shared production facilities solve different problems. A general subsidy cannot substitute for knowing which constraint is binding.

The monitoring system itself should remain light. A consistent panel of firms, a short questionnaire and confidential reporting would be more useful than an elaborate dashboard that entrepreneurs have little time to update. Firms that close or stop responding must also be tracked; otherwise, the disappearance of struggling businesses could make the remaining sample look healthier.

Listen to sentiment, then verify it. Association surveys provide timely access to business experience, but their findings depend on who responds and how respondents interpret conditions. Expectations can change without corresponding changes in production. A survey can identify warning signs; it cannot demonstrate that a particular regulation, financing measure or public programme caused the reported outcome.

For India, enterprise responses should therefore be checked, where feasible and with appropriate safeguards, against invoices, payment records, shipments and actual investment. The purpose is to connect what businesses report with what subsequently happens.

The deeper policy challenge is to recognise deterioration before it becomes closure. A small manufacturer can remain open for years while losing the ability to modernise. By the time that weakness appears in employment or export totals, rebuilding capability may be expensive and slow.

Europe’s barometer offers a useful warning for industrial strategy everywhere: the future of a production system is being decided in today’s postponed investments. The real test of business recovery is whether smaller firms can once again afford—and justify—building their next stage of growth.

Source: "SMEunited, SME Business Climate Index and EU Craft and SME Barometer—Autumn 2026, 9 October 2026" (https://www.smeunited.eu/publications/the-sme-business-climate-index-and-eu-craft-and-sme-barometer-autumn2026). 

Tuesday, October 20, 2026

The Trade War Has No Empty Seats

How the U.S.–China conflict can open one market for India while tightening competition in another

A tariff can close a border to a product. It cannot make the factory producing it disappear. Machines remain, workers need wages, lenders expect repayment, and producers search for another buyer. This is where the consequences of a trade war begin to travel beyond the countries fighting it.

For India, the tempting story is straightforward: if the United States buys less from China, Indian exporters will gain. That opportunity deserves attention. But it is only part of the story. The same Chinese producer losing access to an American customer may compete more aggressively with an Indian firm elsewhere. An exporter can gain an order in the United States while losing margin in another market.

One conflict, four different exposures. In The Remains of the Trade: The U.S.–China Trade War and Its Aftermath, Pol Antràs, Adrian Kulesza and Andrea F. Presbitero examine monthly trade flows and document Chinese exports shifting away from the United States towards third countries. Their September 2026 NBER working paper distinguishes four channels: export competition, import competition, consumer gains and sourcing gains. It also shows why simple comparisons of countries’ export baskets can misrepresent exposure: the scale of the trade shock, existing Chinese penetration and buyers’ ability to switch suppliers matter. 

The practical implication is uncomfortable for national scorecards. A country can experience several of these effects simultaneously. Its consumers may benefit from cheaper goods while domestic manufacturers face stronger competition. Its factories may obtain cheaper inputs while its exporters encounter falling prices abroad. There is no single national experience of trade diversion.

The export opening carries a second competitive front. Consider an illustrative Indian engineering cluster. American buyers begin looking for alternatives to Chinese suppliers. Enquiries rise, samples are requested, and some firms secure trial orders. The cluster appears to be benefiting.

Meanwhile, Chinese suppliers seek customers in markets where those Indian firms already sell. Buyers there demand price reductions. The Indian firms now face two tasks: meeting demanding qualification requirements in a new market and defending margins in established ones.

An export strategy focused only on American enquiries would miss half the commercial problem. Every opportunity map should therefore be accompanied by a competition map.

Cheap inputs can strengthen one factory and weaken its neighbour. Trade diversion also creates tension within domestic production networks. An Indian manufacturer purchasing Chinese components or machinery may benefit from more competitive offers. Lower sourcing costs could support modernisation or improve export pricing.

But a nearby Indian enterprise making a competing component may face greater pressure. What looks like an efficiency gain to the buyer can look like a threat to the supplier.

Policy must examine these relationships before choosing a response. Broad protection can raise costs for downstream exporters. Uncritical dependence on low-priced imports can weaken capabilities that take years to rebuild. The relevant question is which production links improve competitiveness, which face temporary disruption, and which require a credible upgrading programme.

A tariff advantage is borrowed competitiveness. Historically, industrial development has required firms to turn market access into accumulated capability. A favourable tariff gap can help secure an introduction. It cannot guarantee consistent quality, reliable delivery, technical problem-solving or repeat business.

This distinction should guide investment. A factory expanded solely because a competitor faces higher tariffs becomes vulnerable when policy changes. Investment in process control, shorter production cycles, certification and engineering capability has a wider commercial life.

The useful test is simple: would the buyer remain if the tariff advantage narrowed? Firms cannot know the answer with certainty, but they should build their strategy around making it more likely.

Clusters need a commercial response, with clear deadlines. Cluster institutions should screen products simultaneously for substitution opportunities in the United States and stronger Chinese competition across other destinations. The assessment should reach below broad sector labels to specific products, buyer requirements and production capabilities.

Support should then address the barriers between an enquiry and a repeat order: testing, sample development, supplier qualification, production scheduling and working capital. Shared facilities can help smaller firms meet requirements that would be expensive to manage individually.

Public support should have review dates and measurable outcomes. A temporary market opening is a reason to accelerate qualification and productivity investment. It is a weak basis for an indefinite subsidy commitment.

Count what remains after the shipment. Rising exports alone cannot establish commercial success. More shipments may coexist with thinner margins, greater imported content or longer payment delays. The paper’s trade-flow findings should therefore inform strategy without being treated as proof of firm profitability or lasting industrial upgrading.

Indian cluster dashboards should track repeat buyers, domestic value added, realised margins, payment cycles and productivity alongside export growth. These measures reveal whether firms are building a stronger business or merely handling displaced orders.

The future belongs to producers who can survive the return of competition. India’s opportunity is to use a temporary opening to become a supplier buyers continue to choose. The lasting gain from the trade war will be the capability left behind when the tariff window closes.

Source: NBER Working Paper 35785, September 2026. The Indian cluster recommendations are the editorial interpretation developed here.

Sunday, October 18, 2026

How Knowledge Crosses Borders: Why Building Semiconductor Factories Is Not Enough

The old geography of industry is giving way to the new geography of knowledge

For much of industrial history, economic development followed a familiar belief: bring factories together, attract investment, build infrastructure and productivity will gradually improve. Industrial clusters were expected to become centres of technological learning simply because enterprises operated close to one another.

This thinking influenced industrial policy across the world. From the industrial districts of Europe to the export-processing zones of East Asia and the manufacturing clusters of India, governments invested heavily in industrial estates, transport infrastructure, tax incentives and common facilities. The assumption was that knowledge would spread naturally as firms competed, cooperated and observed one another.

But the semiconductor industry raises a fundamental question. What if factories can cross borders without transferring the knowledge that makes them competitive?

The October 2026 CEPR research by Goldberg, Juhász, Lo Forte and Thurk challenges the idea that technological capabilities emerge automatically from geographical concentration. Its central message is that knowledge travels through identifiable economic relationships. Suppliers learn from customers, engineers carry experience between organisations, multinational companies transfer operating practices, and investment creates opportunities for technical interaction.

The important distinction is between the movement of production and the movement of capability. A country can attract billions of dollars in semiconductor investment and still remain technologically dependent if its domestic enterprises and engineers do not participate meaningfully in learning.

Technology does not travel like merchandise

International trade has traditionally been understood as the movement of goods across borders. A semiconductor chip manufactured in Taiwan may be incorporated into equipment designed in the United States, assembled in Vietnam and sold in Europe. The physical product moves through an internationally distributed production system.

Knowledge follows a different geography.

A machine can be purchased, but the ability to operate it at world-class efficiency must be developed. A manufacturing process can be documented, but the experience required to control defects, improve yields, diagnose failures and modify production conditions cannot always be transferred through manuals.

This distinction is especially important in semiconductors, where small variations in manufacturing conditions can determine whether production is commercially viable.

The research draws attention to the channels through which technological learning can occur: supplier relationships, multinational production networks, engineer mobility and foreign direct investment. These relationships matter because they create opportunities for repeated interaction, problem-solving and the exchange of practical knowledge.

An equipment supplier working closely with a semiconductor manufacturer may acquire knowledge that would never emerge from a conventional sales transaction. An engineer moving between firms may bring experience in process optimisation. A multinational company may introduce quality systems, technical routines and production-management practices into a new location.

But none of these transfers is guaranteed. Their effectiveness depends on incentives, institutional arrangements and the ability of receiving firms to absorb and apply knowledge.

The future of industrial competitiveness may therefore depend less on how many factories a country attracts and more on how many learning relationships those factories create.

The semiconductor paradox: global production, concentrated intelligence

Semiconductors represent one of the most internationally connected industries in the world. Design, fabrication, manufacturing equipment, materials, packaging, testing and final applications are distributed across several economies.

Yet technological leadership remains highly concentrated.

The industry illustrates an uncomfortable reality of globalisation. Production networks can become geographically dispersed while control over critical technologies remains concentrated within a relatively small number of companies and countries.

A country may participate in semiconductor assembly without mastering advanced chip design. It may operate fabrication equipment without developing the capability to manufacture that equipment. It may supply chemicals and materials without acquiring the process knowledge required for higher-value production.

This creates different levels of participation within the same global value chain.

At the lowest level, firms provide labour, land, utilities and routine production services. At higher levels, they contribute engineering, process improvement, specialised materials, equipment design and technological innovation.

The difference between these levels is not merely investment. It is accumulated knowledge.

Historically, successful industrial upgrading has required more than the arrival of foreign enterprises. It has depended on domestic firms developing the technical competence to become increasingly sophisticated participants in production networks.

The semiconductor evidence reinforces the need to distinguish foreign investment that creates production capacity from foreign investment that creates domestic technological capability.

Why proximity is not the same as learning

Industrial cluster policy often treats geographical concentration as an economic achievement. The number of enterprises, investment commitments, employment generated and area occupied become the principal indicators of success.

These indicators measure industrial activity. They do not necessarily measure industrial learning.

Consider two semiconductor clusters.

The first attracts a large multinational facility, provides excellent infrastructure and generates substantial employment. However, most advanced engineering services, equipment maintenance, process technologies and specialised inputs continue to come from overseas. Local firms remain confined to construction, transport, packaging and routine services.

The second attracts a smaller investment but establishes technical relationships between the multinational enterprise, domestic suppliers, universities and engineering institutions. Local firms participate in equipment servicing, testing, process improvement, specialised component development and workforce exchanges.

The first cluster may report greater investment. The second may develop stronger foundations for long-term technological independence.

This is a hypothetical comparison, not a measured result from the paper. It illustrates why conventional investment indicators can misrepresent the quality of industrial development.

The essential policy question is no longer whether firms are located near one another. It is whether their relationships produce measurable improvements in technical capability.

A cluster becomes technologically meaningful when proximity is converted into organised learning.

Foreign investment must carry a learning obligation

Foreign direct investment remains essential for countries attempting to enter technologically demanding industries. Advanced semiconductor production requires enormous capital, specialised equipment, reliable infrastructure and access to international customers.

However, the traditional investment-promotion model concentrates heavily on attracting the initial project.

Governments offer fiscal incentives, subsidised land, infrastructure support, tax concessions and regulatory facilitation. Once the investment is secured, employment and output become the principal measures of success.

The next generation of industrial policy must go further.

Public incentives should encourage engineering exchanges, supplier-development programmes, local technical recruitment, collaborative testing, equipment-maintenance capabilities and structured knowledge-sharing arrangements.

Such obligations must be commercially realistic and compatible with intellectual-property protections and applicable trade rules. Companies cannot simply be required to surrender proprietary technology. But public support can be designed to reward genuine technical collaboration and local capability development.

A multinational semiconductor manufacturer receiving substantial public incentives could, for example, be encouraged to develop qualified domestic suppliers, support joint engineering projects and establish technical training programmes with measurable outcomes.

The objective should not be forced localisation of every input. It should be progressive localisation of technological competence.

This is a major conceptual shift: investment incentives should reward the creation of learning capacity, not merely the installation of production capacity.

Engineers may be more important than industrial estates

One of the most consequential channels of knowledge transfer is the movement of skilled people.

Engineers carry more than formal qualifications. They accumulate experience in solving production problems, managing equipment, interpreting technical failures, improving processes and coordinating complex manufacturing systems.

Much of this knowledge is tacit. It develops through practice and is difficult to reproduce through classroom instruction alone.

When experienced engineers move between organisations, they can help transfer technical routines and problem-solving capabilities. When domestic engineers participate in international production networks, they gain exposure to operating standards and technological practices that may be difficult to acquire locally.

For developing economies, this suggests that international engineering exchanges, industrial apprenticeships, returning technical professionals and collaborative research programmes should be treated as central components of industrial policy.

However, mobility alone is insufficient. Knowledge becomes economically valuable when engineers have opportunities to apply what they have learned.

A highly trained engineer returning to an enterprise without suitable equipment, technical autonomy or investment resources may be unable to translate experience into productivity gains.

Therefore, the challenge is not simply to train or attract engineers. It is to build enterprises capable of using their knowledge.

India's semiconductor ambition needs a second industrial strategy

India has increasingly recognised semiconductors and electronics as strategic industries. Investment incentives, semiconductor manufacturing initiatives, electronics production schemes and infrastructure development have created a stronger policy framework for attracting global production networks.

These efforts are important, but they represent only the first stage of technological development.

India's deeper challenge is to ensure that emerging semiconductor and electronics investments generate capabilities beyond the immediate facilities.

This requires a second industrial strategy centred on learning.

Semiconductor and electronics clusters in Gujarat, Karnataka, Tamil Nadu, Uttar Pradesh and other emerging locations should develop structured mechanisms connecting anchor investors with domestic engineering firms, equipment-service providers, technical institutions and specialised MSMEs.

Supplier development must move beyond vendor registration. Firms need assistance with process control, precision manufacturing, quality management, reliability testing, certification and technical documentation.

Engineering institutions should be evaluated not only by the number of graduates produced but also by their participation in industrial problem-solving.

Common facilities should include advanced testing, metrology, reliability assessment and process-development services where commercially and technically feasible.

Public support should help smaller enterprises cross the expensive threshold between being potential suppliers and becoming technically qualified suppliers.

The crucial question is whether India can build an ecosystem capable of learning from the semiconductor industry rather than remaining primarily a destination for semiconductor investment.

The next industrial divide will be between producers and learners

The historical division between developed and developing economies was often described in terms of capital, infrastructure, labour productivity and access to markets.

The emerging division may be more complex.

Some economies will participate in advanced manufacturing while remaining dependent on imported process knowledge, equipment, intellectual property and engineering services. Others will use participation in global production networks to build progressively stronger domestic technological capabilities.

Both may report rising industrial output. But their long-term economic trajectories could diverge sharply.

Artificial intelligence, automation and advanced manufacturing may intensify this divide. As production becomes more sophisticated, competitive advantage will increasingly depend on the ability to understand, adapt and improve technologies rather than simply operate them.

Countries that fail to develop domestic learning systems risk becoming technologically dependent manufacturing locations.

This does not mean every country must independently produce every technology. Complete technological self-sufficiency is neither practical nor necessarily efficient.

The more realistic objective is technological agency: the capacity to understand critical processes, develop specialised expertise, negotiate effectively with technology providers and progressively move into higher-value activities.

A necessary caution: semiconductors are not every industry

The semiconductor industry offers powerful insights, but it also has distinctive characteristics. Production is exceptionally capital-intensive, technical standards are demanding, intellectual-property barriers are substantial and international production networks are highly specialised.

Learning mechanisms observed in semiconductors cannot automatically be assumed to operate with the same strength in garments, leather, handicrafts, food processing or other labour-intensive industries.

In traditional clusters, informal apprenticeship, labour circulation, subcontracting relationships, collective marketing and local entrepreneurial imitation may remain important.

The appropriate lesson is not that geographical spillovers are irrelevant everywhere. It is that policymakers must identify the actual mechanisms through which knowledge moves within each industry.

Moreover, empirical findings about knowledge transmission depend on the research design and its identification assumptions. Evidence of a particular transmission channel should not automatically be interpreted as proof that every policy intervention targeting that channel will succeed.

The value of the research lies in directing attention toward mechanisms that can be investigated, strengthened and measured.

From cluster development to knowledge-network development

The conventional industrial cluster was largely defined by geographical concentration. The future cluster may be defined increasingly by the density and quality of its technical relationships.

This does not make physical infrastructure unimportant. Reliable electricity, logistics, industrial land and utilities remain essential. But they provide the conditions for production, not a guarantee of technological upgrading.

A more advanced cluster-development model would assess whether enterprises are developing new products, improving production processes, qualifying for demanding customers, acquiring engineering skills and entering more sophisticated segments of global value chains.

Cluster institutions would become organisers of technical collaboration rather than merely administrators of common infrastructure.

Their responsibilities could include coordinating supplier qualification, facilitating engineering exchanges, organising joint problem-solving, linking firms with research institutions and helping enterprises access specialised technical services.

The success of such institutions should be measured through capability outcomes: reduced defect rates, higher yields, successful supplier qualifications, domestic engineering solutions and sustained participation in higher-value production activities.

This is a more demanding form of cluster development because it requires continuous institutional engagement rather than one-time infrastructure expenditure.

The future belongs to economies that organise learning

The most important implication of the CEPR research is that international production does not automatically produce international knowledge convergence.

Globalisation creates opportunities for technological learning, but these opportunities must be converted into capabilities through firms, people, institutions and sustained economic relationships.

The semiconductor industry makes this distinction unusually visible. A factory can be built within a few years, while the engineering competence surrounding it may take decades to develop.

For India and other emerging manufacturing economies, the policy challenge is therefore not simply to attract the next global semiconductor plant. It is to ensure that each major investment leaves behind a deeper domestic technological ecosystem.

The ultimate measure of industrial progress should not be how much foreign technology a country can operate, but how much technological capability its enterprises and workers can progressively develop.

The industrial policy of the twentieth century concentrated factories. The industrial policy of the twenty-first century must organise learning.

And the countries that understand this distinction will be better positioned to capture the real economic value of global manufacturing.

Research reference: The CEPR paper was published on 2 October 2026. The publisher confirms that cross-border technological learning operates through supply-chain relationships, engineer mobility within multinationals and foreign investment, rather than relying solely on anonymous spillovers.

The official author names are Pinelopi Koujianou Goldberg, Réka Juhász, Giulia Lo Forte and Jeff Thurk.

[Read the original CEPR Discussion Paper 22009](https://cepr.org/publications/dp22009?utm_source=chatgpt.com)

Saturday, October 17, 2026

The Future Factory Needs Future-Ready Suppliers


Why India’s manufacturing transformation must reach beyond the large plant

A modern factory can stand behind impressive gates while its suppliers struggle with outdated machines, uncertain orders and shortages of technical skills. The factory may be globally connected, but the surrounding production economy can remain fragile. This is the uncomfortable possibility behind industrial strategies that celebrate major investments without asking whether smaller enterprises can participate in the industries being created.

The OECD’s Fit-for-Future Manufacturing SMEs: Effective Policies for Transformation, published on 2 October 2026, brings this question into focus. Examining automotive, semiconductor and electronics, and machinery businesses across France, Germany, Japan, Korea and the United States, it shows why industrial transformation requires policies shaped around the position of smaller firms within particular supply chains. (oecd.org⁠)

The old assumption has become expensive. Industrial development has often been imagined as a spreading process: attract a large manufacturer, expand production and allow knowledge, orders and technology to reach smaller suppliers. Such linkages can develop. But physical proximity alone cannot create them. A small enterprise located beside an advanced plant may still lack the testing capability, technical documentation or production consistency needed to supply it.

The OECD explicitly challenges the assumption that support for major industries will automatically benefit SMEs. It finds that direct, structured SME support often remains secondary to measures aimed at larger enterprises. Its central contribution is to examine digitalisation, low-carbon production and supply-chain disruption together, while recognising that their effects differ by industry. (oecd.org⁠)

For India, the implication is significant: manufacturing policy needs to finance the connections between firms as deliberately as it finances the factories themselves.

Three transformations arrive at the same workshop. Consider a hypothetical component manufacturer. One customer asks for digital production records. Another wants energy and emissions information. A third requires alternative sources for critical inputs. Each request appears reasonable in isolation. Together, they demand investment, management time and new skills before additional revenue is assured.

Public programmes can make this harder when they treat technology, energy efficiency and resilience as separate administrative subjects. The enterprise experiences one business problem, while support arrives through several application forms.

An Indian supplier programme should therefore begin with a practical diagnosis: which changes will help this firm retain customers, enter a viable market or reduce a measurable operating risk? Funding should follow that sequence. Buying software before stabilising production records, or installing equipment before securing the skills to operate it, can leave expensive assets underused.

Automotive policy must start with the component’s future. The transition towards electric powertrains creates particular difficulties for suppliers whose capabilities and revenues depend on internal-combustion-engine components. The OECD identifies adaptation to new vehicle supply chains, or movement into other industries, as a central challenge for these businesses. (oecd.org⁠)

For Indian automotive clusters, the first task should be to map exposure at the product level. Which components face declining demand? Which machining, casting, tooling or quality-control capabilities can serve new customers? Which investments remain commercially useful across several possible transition speeds?

Support could then combine traceability, engineering assistance, prototype testing and diversification finance. A technically capable firm should not be encouraged into an unfamiliar EV product simply because that category attracts policy attention. Its transition needs a credible customer, an achievable specification and a workable margin.

Electronics policy must build a route to qualification. A major electronics or semiconductor investment does not automatically create an accessible market for nearby small firms. The OECD highlights high entry barriers alongside opportunities in specialised components, design and maintenance services. (oecd.org⁠)

India’s practical response should be to identify specific supply opportunities and work backwards from buyer requirements. A prospective supplier needs to know what must be tested, who can validate it, how long approval may take and what the process will cost.

Shared laboratories would help only if their capabilities and results are accepted by prospective buyers. Skills programmes should address actual production and engineering gaps. Access to design tools and intellectual property should be arranged through lawful, commercially workable licences.

Above all, finance should recognise the period between developing a credible product and receiving an approved commercial order. Otherwise, a technically promising enterprise can run out of money while waiting to become a supplier.

Machinery firms need a business-model transition. The OECD’s machinery analysis describes opportunities in digitally enabled services, alongside barriers involving investment, skills and organisational change. Smaller manufacturers can struggle to move beyond hardware production even when new service markets are emerging. (oecd.org⁠)

For India, this suggests a wider agenda than subsidising new machines. A machinery enterprise could earn revenue through installation, remote diagnostics, retrofits, maintenance and application-specific customisation. These services require software capability, reliable field support and a clear agreement on access to customer data.

Cluster institutions could provide shared engineering and digital-service teams that individual firms cannot yet afford. Their performance should be judged by functioning services and paying customers. A demonstration centre that impresses visitors but changes no commercial practice has limited developmental value.

Public incentives should purchase supplier capability. A policy proposal follows from this analysis: large firms receiving public support should agree to proportionate, measurable supplier-development commitments.

These commitments could cover technical mentoring, supported qualification trials, predictable payment practices and verified improvements among participating suppliers. They should distinguish between suppliers merely attending a workshop, suppliers passing qualification and suppliers receiving repeat commercial orders.

Care is needed. A domestic procurement target alone may reward superficial localisation. An obligation to hold training sessions may generate attendance sheets rather than competence. The stronger test is whether suppliers can consistently meet specifications, improve productivity and compete for business beyond the original anchor firm.

Supplier development should expand a smaller enterprise’s commercial options. It should not create permanent dependence on one powerful customer.

Borrow the questions, test the answers locally. The OECD study offers a comparative diagnosis, not causal proof that particular programmes deliver particular outcomes. Its five-country setting also differs substantially from the institutional and technological conditions of many Indian clusters. The country analysis draws on sector evidence, policy reviews and stakeholder interviews. (oecd.org⁠)

India should use these insights to design and test focused interventions. Begin with a defined supplier group, establish its starting capabilities, track results over time and examine whether improvements exceed what would otherwise have occurred. Publish failures alongside successes. This would provide a firmer basis for expansion than counting beneficiaries or expenditure alone.

The future of manufacturing will be shaped by the capabilities distributed across thousands of smaller enterprises. A large plant can introduce advanced production. A capable supplier network can make that advancement durable, adaptable and locally rooted.

India’s industrial ambition should be measured by how many smaller firms become capable of supplying the next generation of industry—and how much knowledge, bargaining power and value they retain while doing so.

Read the OECD report⁠


Friday, October 16, 2026

Why Trade Growth No Longer Guarantees Development


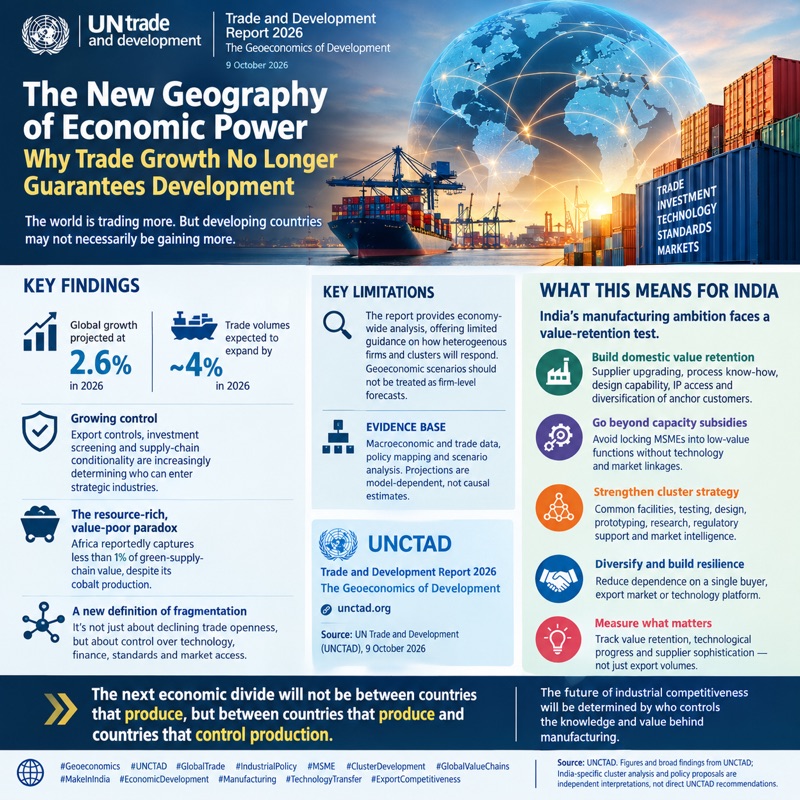
Based on UN Trade and Development (UNCTAD), Trade and Development Report 2026: The Geoeconomics of Development | 9 October 2026

The World Is Trading More, but Development Is Becoming Harder

For much of the twentieth century, economic development followed a relatively simple assumption: countries that produced more, exported more and attracted foreign investment would gradually become richer. Industrialisation created employment, exports generated foreign exchange, and participation in global markets opened opportunities for technological learning.

That assumption is becoming increasingly unreliable.

The global economy is entering a period in which the volume of international trade may continue to expand while the opportunities for developing countries to capture its benefits become more restricted. Goods can cross borders, investment can flow between countries, and multinational companies can expand their supply chains without necessarily transferring technology, productive knowledge or economic power.

The Trade and Development Report 2026: The Geoeconomics of Development, published by UN Trade and Development on 9 October 2026, brings this contradiction into focus.

The report projects global economic growth of approximately 2.6% in 2026, even as international trade volumes expand by roughly 4%. These figures suggest that trade activity can grow faster than the world economy without producing a corresponding improvement in development opportunities.

The deeper concern is not whether globalisation is ending. It is whether globalisation is being reorganised into a system in which a relatively small number of countries and corporations control the most valuable parts of production.

The emerging development question is therefore no longer simply how much a country exports, but how much knowledge, technology, income and decision-making power it retains from those exports.

From Free Trade to Controlled Interdependence

The economic history of globalisation has passed through several distinct phases.

The post-war period emphasised industrial reconstruction, domestic manufacturing capabilities and national development strategies. The liberalisation era of the 1980s and 1990s promoted open markets, lower tariffs, foreign investment and integration into international production networks.

The next phase was dominated by global value chains. Production was divided across countries according to costs, capabilities and logistics. Developing economies became important suppliers of components, raw materials, intermediate goods and labour-intensive manufactured products.

This arrangement created enormous opportunities, particularly in East Asia. But it also produced a structural weakness: participation in a global value chain did not automatically translate into control over that chain.

The emerging geoeconomic order is making this weakness more visible.

Governments increasingly influence industrial development through export controls, investment screening, technology restrictions, strategic subsidies, national security requirements and supply-chain conditions.

Semiconductors, batteries, artificial intelligence, pharmaceuticals, telecommunications, critical minerals and advanced machinery are no longer treated merely as commercial industries. They are becoming instruments of national economic security.

This changes the rules of industrial competition.

A developing country may have competitive labour, natural resources, industrial land and attractive investment incentives, yet remain excluded from high-value production because it lacks access to technology, intellectual property, finance, specialised equipment or approved international supply networks.

Tariffs once determined much of the cost of entering a foreign market. Increasingly, technology permissions, standards, ownership conditions and strategic trust determine whether entry is possible at all.

The world is moving from open competition based largely on production costs towards controlled interdependence based on technological and institutional power.

The Resource-Rich, Value-Poor Paradox

Perhaps the most revealing contradiction in the emerging global economy is that countries supplying essential resources may capture only a small fraction of the value ultimately generated.

Africa illustrates this problem.

Despite its substantial role in supplying minerals such as cobalt, the continent reportedly captures less than 1% of the value associated with green supply chains, according to the report’s analysis.

The economic significance extends far beyond mining.

A mineral extracted in a developing economy may be processed elsewhere, converted into advanced materials in another country, incorporated into batteries or electronic systems in a third, and ultimately sold as a high-value product under a global brand.

At every stage, value is added through technology, processing, design, intellectual property, financing, logistics and market access.

The country supplying the original resource may receive relatively little of that accumulated value.

This is not simply a problem of unequal prices. It is a problem of unequal productive capabilities.

Countries that control design, patents, sophisticated processing, technical standards and customer relationships occupy the most profitable positions. Countries restricted to extraction, basic processing or low-cost assembly remain vulnerable to commodity cycles and buyer decisions.

The same problem exists in garments, electronics, pharmaceuticals, automotive components and agricultural processing.

A country may become a major exporter without becoming a major owner of the knowledge embedded in what it exports.

This is the central paradox of modern development: a country can become indispensable to global production while remaining economically dependent on those who control the production system.

Industrial Policy Is Returning, but Not on Equal Terms

Industrial policy has returned to the centre of economic strategy.

Advanced economies increasingly use public funding, procurement, tax incentives, research support and strategic regulations to strengthen domestic production. Technologies once allocated mainly through global markets are now being actively supported or restricted by governments.

For developing countries, this creates both opportunities and risks.

New investment may arrive as multinational corporations diversify production locations. Supply-chain restructuring may create demand for alternative manufacturing destinations. Strategic competition may encourage technology partnerships and infrastructure investment.

However, these opportunities are not distributed equally.

Countries with strong research institutions, skilled workers, reliable infrastructure, domestic supplier networks and negotiating capacity are better positioned to benefit. Economies offering only low wages and financial incentives may attract factories without acquiring lasting industrial capabilities.

A subsidised manufacturing facility can generate employment and exports. But if its machinery, designs, critical components, software and major customers remain externally controlled, the host economy may capture only a limited share of the value created.

Industrial policy must therefore be judged by more than the number of factories established or the investment commitments announced.

The important questions are whether domestic suppliers have moved into more sophisticated functions, whether local firms have acquired process knowledge, whether engineering capabilities have improved, and whether the country can eventually produce, design or adapt technologies independently.

Industrialisation without technological learning risks becoming a more expensive form of dependency.

India’s Manufacturing Ambition Faces a Value-Retention Test

India occupies an unusual position in this changing economic landscape.

It has a large domestic market, substantial engineering capabilities, a growing digital economy, an established pharmaceutical industry and significant manufacturing clusters. Its geopolitical position also creates opportunities as companies seek to diversify production beyond concentrated supply networks.

Yet India’s manufacturing challenge is not merely to attract more production.

It is to retain more value from that production.

Consider electronics. Domestic assembly can expand rapidly while high-value semiconductors, advanced displays, operating systems, intellectual property and precision manufacturing equipment continue to originate elsewhere.

In pharmaceuticals, India has built considerable strength in formulations and process chemistry, but important dependencies remain in selected active pharmaceutical ingredients, advanced biotechnology and sophisticated medical technologies.

In textiles, competitive production clusters may generate substantial exports while international buyers retain control over brands, product development, distribution networks and consumer relationships.

In capital goods, increasing machinery output does not necessarily mean domestic control over advanced sensors, precision components, industrial software or critical control systems.

These examples demonstrate why manufacturing growth and industrial capability must be evaluated separately.

India’s next industrial transition should not be measured only by how much it produces for the world, but by how much technological and commercial authority Indian enterprises acquire within global production networks.

The difference will determine whether India becomes a durable industrial power or remains primarily a competitive manufacturing location.

The Missing Link in Cluster Development

The implications for India’s MSME clusters are particularly significant.

For decades, cluster development programmes have concentrated on infrastructure, common facilities, skills, credit, technology upgrading and market access. These interventions have produced benefits, but many clusters remain dependent on external technology suppliers, large buyers and intermediaries.

The new geoeconomic environment requires a more demanding approach.

A textile cluster in Tiruppur should not evaluate success only through garment output and export growth. It should also assess progress in technical textiles, sustainable processing, product development, traceability, proprietary designs and direct customer relationships.

An automotive cluster in Pune or Gurugram must move beyond component supply towards engineering, testing, embedded electronics, specialised materials and electric-mobility technologies.

A pharmaceutical cluster in Hyderabad should measure not only manufacturing capacity but also its strength in research, complex molecules, process technologies and regulatory knowledge.

An electronics cluster in Noida should build deeper local supplier networks and capabilities in component engineering, testing, industrial design and production technologies rather than depend indefinitely on imported kits and systems.

The objective is not to eliminate imports or reject foreign investment. Such an approach would be economically unrealistic.

The objective is to ensure that international integration creates cumulative domestic capabilities.

This requires a fundamental change in the way cluster programmes are designed.

Rather than treating a cluster simply as a geographical concentration of enterprises, policymakers should treat it as a system for acquiring, developing and retaining industrial knowledge.

Public support should be linked to measurable improvements in supplier sophistication, engineering capability, product development, technology access and customer diversification.

Common facility centres should evolve from shared machinery installations into institutions providing testing, design, prototyping, applied research, regulatory intelligence and technological problem-solving.

Cluster associations should move beyond representing industry grievances and become organisations capable of negotiating technology partnerships, building market intelligence and coordinating supplier upgrading.

Most importantly, anchor investors receiving public incentives should be encouraged, through practical and enforceable arrangements, to develop domestic suppliers, support technical learning and create opportunities for local firms to undertake higher-value functions.

Otherwise, public subsidies may strengthen production capacity while leaving the underlying structure of dependency unchanged.

From Export Competitiveness to Value-Retention Competitiveness

The traditional definition of export competitiveness focuses on price, quality, delivery and market access.

These factors remain essential. But they are no longer sufficient.

A more useful development framework should examine the share of value that remains within the domestic economy after accounting for imported inputs, foreign technology payments, external services and the distribution of profits across the production network.

Even domestic value added is not the complete measure. Some domestic activities may generate substantial employment but limited opportunities for technological upgrading, while others create knowledge that can be applied across many industries.

Future competitiveness therefore needs two dimensions.

The first is the ability to enter and remain competitive in international markets.

The second is the ability to move progressively into activities that generate greater technological knowledge, stronger bargaining power and more sustainable domestic income.

For India, this suggests a shift from export promotion alone towards strategic value retention.

Supplier development programmes should identify specific technologies and components that domestic enterprises can realistically master. Public research institutions should work more closely with industrial clusters. Technology-transfer agreements should contain credible provisions for learning and capability development.

MSMEs should also reduce excessive dependence on a single multinational buyer, export market or technological platform.

Diversification is not simply a commercial risk-management tool. It is increasingly a form of economic security.

The Danger of Misreading Geoeconomic Forecasts

The UNCTAD analysis offers an important framework for understanding structural changes in the world economy, but its findings must be interpreted carefully.

Global projections are dependent on modelling assumptions, while policy mapping and scenario analysis identify risks and possible outcomes rather than establish causal effects for individual enterprises.

A semiconductor supplier, garment exporter and food-processing MSME will not experience geopolitical fragmentation in the same way.

Some firms may lose market access because of new restrictions. Others may gain business as buyers diversify. Certain clusters may benefit from strategic investment, while others may face higher compliance and technology costs.

Therefore, national industrial strategies cannot simply translate global forecasts into uniform cluster policies.

They need detailed evidence on firm capabilities, imported technology dependence, buyer concentration, local value addition and realistic upgrading opportunities.

A cluster-level geoeconomic risk dashboard could become a valuable policy instrument, combining information on export-market exposure, technology dependencies, critical inputs, standards and potential alternative customers.

Such an approach would make industrial policy more adaptive and less dependent on broad announcements.

The Next Development Divide Will Be Between Producers and Controllers

The most consequential change in the global economy may not be the division between countries that trade and countries that do not.

It may be the division between countries that participate in production and countries that control its most valuable functions.

The first group supplies labour, resources, factory capacity and intermediate goods.

The second controls technology, design, finance, standards, intellectual property, platforms and customer access.

This distinction is not absolute. Countries can move between these positions through learning, investment, institutional development and strategic partnerships. The experience of successful industrial economies demonstrates that upgrading is possible, although it is neither automatic nor guaranteed.

For developing economies, the challenge is to use participation in global value chains as a pathway towards greater capabilities rather than accept a permanent position at their lower-value stages.

India’s opportunity is substantial, but the window will not remain open indefinitely.

As strategic technologies become more tightly controlled and global supply chains become more politically conditioned, latecomers may find it increasingly difficult to acquire the knowledge needed for industrial advancement.

The next generation of industrial policy must therefore invest not only in factories, but also in the capabilities that determine who controls those factories, who designs their products, who owns their technologies and who ultimately captures their profits.

The Future: Development Is No Longer About Joining the Global Economy. It Is About Changing One’s Position Within It.

The defining question for the coming decade is not whether international trade will continue growing. It almost certainly will, although the pace and direction remain uncertain.

The question is who will capture the value generated by that trade.

Developing countries can increase exports, attract foreign investment and expand manufacturing employment while remaining dependent on external technology, finance and market decisions.

That is why the geoeconomics of development demands a new industrial policy framework.

For India, particularly its MSME clusters, the priority must shift from subsidising capacity to building capability, from attracting anchor investors to developing domestic supplier networks, and from measuring export volumes to measuring value retention and technological progress.

The industrial winners of the future will not necessarily be the countries that manufacture the most. They will be the countries that progressively control more of what makes manufacturing valuable.

And that is the real challenge posed by the emerging geoeconomics of development.

Source and verification: The report’s publication date, global growth forecast of 2.6%, and projected trade growth of approximately 4% are confirmed by UNCTAD. The India-specific cluster analysis and policy proposals are independent interpretations rather than direct UNCTAD recommendations.

Original report: UNCTAD — Trade and Development Report 2026⁠


The Great International Economic Reordering: Who Will Control Value in 2035?

The future of global economic power may belong not to countries that manufacture the most, but to those that control the knowledge, technolo...