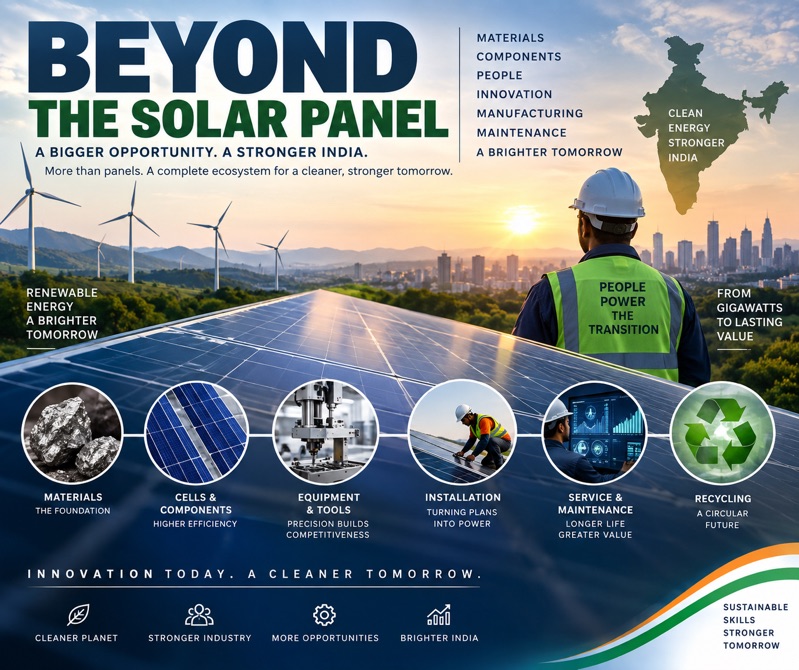
 The panel is visible. The industrial system behind it is not. For much of the public discussion on renewable energy, progress is measured in gigawatts. More solar capacity means a faster energy transition. More factories mean stronger domestic manufacturing. But industrial history tells us that these numbers can hide as much as they reveal. A country can install enormous quantities of equipment without capturing an equally large share of the technology, components, engineering knowledge, services and profits behind that equipment. India’s next renewable-energy challenge is therefore no longer simply how many solar panels it can install. The more difficult question is how much industrial capability India can build around every panel, turbine, inverter, mounting structure, cable, enclosure and maintenance contract.
From importing energy to importing energy equipment. India’s earlier energy dependence was largely about oil, gas and coal. The renewable transition changes the technology, but it does not automatically eliminate dependence. Solar power requires cells, wafers, modules, glass, encapsulants, power electronics, structures, specialised machinery, testing systems and increasingly storage. Wind requires blades, towers, generators, gearboxes, castings, control systems and sophisticated maintenance capabilities. The energy transition can therefore replace one form of dependence with another unless domestic industry moves deeper into these value chains. This concern is already reflected in policy: in March 2026, the government extended the Approved List of Models and Manufacturers framework to solar ingots and wafers from June 2028, explicitly seeking greater domestic value addition further upstream in the solar supply chain. (Press Information Bureau)
164.59 GW is an energy achievement, not automatically an industrial achievement. India reached 164.59 GW of installed solar generation capacity by 31 July 2026, compared with only about 2.8 GW in 2014. Wind generation capacity reached 58.14 GW. These are remarkable changes in the physical structure of the Indian electricity system. But installed generation capacity should not be confused with manufacturing output, domestic value addition or technological ownership. Separately, India had developed around 24 GW of annual wind-turbine manufacturing capacity by March 2026. These figures measure different things and should not be added together or treated as evidence of the same industrial capability. (Press Information Bureau)
This distinction will become increasingly important. A country may manufacture a final product while importing high-value materials, specialised equipment or critical components. It may have factories without owning process technology. It may have large installed manufacturing capacity without operating those factories at high utilisation. And it may produce enormous volumes while earning relatively thin margins. The future industrial question is therefore not simply Make in India. It is what India knows how to make, how reliably it can make it, and how much value remains inside the domestic economy after the product is sold.
The real renewable factory is an ecosystem. Industrial development rarely happens inside one large factory. Around successful industries emerge hundreds of specialised suppliers making components, tooling, fixtures, electrical systems, packaging, testing equipment and maintenance solutions. They accumulate knowledge gradually. One enterprise learns precision fabrication. Another masters coatings. Another becomes excellent at electrical enclosures. Another develops testing capability. Over time these apparently small capabilities become the industrial infrastructure that makes the larger industry competitive.
This is where the renewable transition becomes especially important for MSMEs. Most small firms should probably not begin by asking whether they can manufacture a solar panel or wind turbine. They should ask a narrower and commercially harder question: what recurring problem in the renewable supply chain can this enterprise solve better than somebody else?
The opportunity could be precision components, mounting structures, junction boxes, specialised fasteners, electrical enclosures, connectors, cable-management systems, fabrication, specialised tools, monitoring equipment, repair services, testing, refurbishment or preventive maintenance. Each opportunity has a different technological threshold. Each has different customers, standards, machinery, certification requirements, warranty risks and working-capital cycles.
That distinction matters because the easiest renewable opportunity to enter may not be the best one to remain in.
Assembly creates scale. Capability creates survival. India has experienced this lesson before. Industrialisation after Independence placed heavy emphasis on machinery and domestic production. Liberalisation after 1991 brought global technology, foreign components and competitive pressure. In several sectors India became highly capable in manufacturing and assembly, but remained dependent on imported technologies or critical components further upstream. Renewable manufacturing risks repeating that pattern on a much larger scale.
The dangerous assumption is that once a factory exists, competitiveness has been created. A factory is only the physical shell of competitiveness. The deeper assets are process knowledge, yields, quality consistency, engineering capability, supplier development, product improvement and customer confidence.
A renewable component that fails after several years creates costs far beyond its purchase price. Reliability therefore becomes an industrial currency. Suppliers able to demonstrate predictable performance can gradually move from being low-cost vendors to trusted engineering partners.
Clusters must become laboratories rather than industrial addresses. India has many industrial clusters, but the renewable transition requires something more sophisticated than geographic concentration. A cluster becomes strategically useful when firms can learn faster because they are located together.
Common facilities should therefore move beyond buildings and machines. They should help firms conduct materials testing, prototype development, process trials, calibration, product validation and workforce training. But there is an important condition: the market must trust the results. A testing centre that buyers do not recognise is infrastructure without economic power.
The next generation of cluster policy should consequently be measured not merely by how many firms use a facility, but by whether firms improve rejection rates, enter new supply chains, qualify with larger customers and eventually export.
Technology cycles are becoming shorter than investment cycles. This may become the biggest danger for renewable MSMEs. Technology can change faster than a small firm’s machinery loan can be repaid. Solar efficiency is improving. Cell architectures are changing. Storage technologies are evolving. Power electronics are becoming more sophisticated. Digital monitoring is expanding. Recycling will eventually become a major industrial activity.
An MSME investing heavily in a process designed around one technology, one specification or one customer can therefore become vulnerable very quickly.
The safer long-term investment may sometimes be in adaptable capability rather than maximum capacity. Precision engineering skills, quality systems, electronics integration, testing capability, materials knowledge and trained technicians can migrate across products. A narrowly configured production line may not.
This changes the meaning of industrial policy. Instead of only encouraging firms to buy machines, policy must help firms learn how to keep changing what those machines produce.
The next renewable opportunity may actually begin after installation. India’s enormous installed base will itself create another economy. Every solar system and wind turbine begins ageing from the day it is commissioned. Modules need inspection. Inverters fail. Structures corrode. Cables deteriorate. Components require replacement. Performance must be monitored. Eventually equipment must be refurbished, recycled or disposed of.
This means the renewable economy of the 2030s will not simply be an installation economy. It will increasingly become an operations, maintenance, diagnostics, refurbishment and circular-economy industry.
For MSMEs this could be particularly significant because service markets are often geographically distributed and less dependent on gigantic production plants. Local enterprises with trained technicians, digital monitoring capabilities and dependable spare-parts networks could build recurring revenue rather than depending entirely on one-time equipment sales.
India must move from gigawatts to value captured per gigawatt. Installed renewable capacity tells us how rapidly the electricity system is changing. Manufacturing capacity tells us how much equipment factories could potentially produce. Neither tells us enough about domestic value addition, profitability, technological depth or the resilience of the supplier network.
The more useful future question may therefore be different.
For every additional gigawatt India installs, how much engineering knowledge, component manufacturing, skilled employment, intellectual property, maintenance capability and export potential remains in India?
That is the number industrial policy should increasingly care about.
India has already demonstrated that it can create one of the world’s largest renewable-energy markets. The next transformation is harder. It must convert that market into an industrial learning system.
The solar panel should not be seen as the end product of India’s renewable strategy. It should be seen as the front door to a much larger manufacturing economy.
Beyond that door lie materials, components, machines, testing, software, storage, maintenance, recycling and thousands of specialised suppliers.
The countries that dominate the renewable economy of the future may not simply be those that install the most gigawatts. They will be those that learn how to capture the greatest industrial value behind every gigawatt.
The official data support the key distinction in your premise: the 164.59 GW figure is installed solar generation capacity, while roughly 24 GW refers to wind-turbine manufacturing capacity as of March 2026. They should not be treated as equivalent measures of manufacturing strength.
#RenewableEnergy #SolarManufacturing #MSME #Manufacturing #EnergyTransition #MakeInIndia #IndustrialDevelopment


No comments:
Post a Comment